
Know your home coverage
Homeowners Insurance in Texas
Compare homeowners insurance for a house you own and live in. Our Texas team helps you review rebuilding limits, roof terms, deductibles and what you could pay after a covered loss.
Already a client? Get help with your policy.
Own a condo unit? See Condo Insurance for coverage reviewed alongside your association’s master policy.
Coverage for your house, your belongings, and life at home.
Before you choose
Compare home insurance beyond the premium.
Two quotes can look similar until you compare what happens after a loss. These are useful questions to put side by side.
Is the rebuilding amount right?
The cost to rebuild is different from market value. Ask how the estimate accounts for your home’s size, materials, and improvements.
How would the roof and belongings be paid?
Replacement cost generally reflects today’s repair or replacement cost. Actual cash value subtracts depreciation. Your roof may have different terms, and part of a replacement-cost payment may wait until repairs are complete.
See OPIC’s explanation of replacement cost and actual cash value.
What would the deductible be in dollars?
A wind or hail deductible may be separate. A percentage deductible is usually based on the dwelling limit, not the repair bill.
Illustration only. Your policy shows your deductible. Read TDI’s guide to deductibles.
Same home. Different terms.
Hypothetical comparison only. These are not actual quotes, available products, or a claim estimate. Both examples use a $300,000 dwelling limit.
| Compare | Example A | Example B |
|---|---|---|
| Wind or hail deductible | 2% = $6,000 | 1% = $3,000 |
| Roof settlement | Actual cash value: depreciation reduces the payment. | Replacement cost: some payment may depend on completing repairs. |
| What to weigh | If the premium is lower, weigh that saving against the deductible and depreciation. | Weigh any higher premium against the deductible and replacement-cost terms. |
A deductible is only one part of what you may pay. Coverage, exclusions, limits, endorsements, and repair requirements still govern each policy. The roof settlement terms must be checked separately from the dwelling limit.
What the policy can help with
What does homeowners insurance cover?
A homeowners policy typically combines property coverage with liability protection.
For the coverage basics, read TDI’s homeowners insurance guide.
- The house
- Dwelling coverage helps repair or rebuild the home after covered damage. The rebuilding estimate matters more here than what you paid for the property.
- Other structures
- A detached garage, fence, or shed may have its own coverage limit. Point out structures beyond the house so they are part of the conversation.
- Your belongings
- Furniture, clothing, and other personal property can be covered at home and sometimes away. Jewelry and other valuables may need more than the standard limit.
- A place to stay
- Additional living expense coverage helps with extra costs, such as lodging and meals, when covered damage makes your home unlivable. Dollar and time limits matter.
- Personal liability
- This can help with certain injuries or property damage you are legally responsible for. Tell us about a pool, pets, or other features that deserve a closer look. Ask whether a personal umbrella could provide additional liability protection.
- Medical payments
- This separate coverage can help with medical bills for certain injuries to other people. It has its own limit.
Own a boat? Review boat insurance alongside your home policy.
Texas weather & water
Wind, hail, and water damage.
Wind & hail
Check whether these losses are included, what deductible applies, and how the roof’s age affects a claim payment.
Leaks & backups
Sudden, accidental plumbing damage may be covered; a continuing leak or maintenance problem can be treated differently. Ask whether sewer or drain backup needs an added endorsement and its own limit.
Flooding
Most homeowners policies exclude flood damage from rising water. Bring flood questions into the conversation early so you can understand what would need separate coverage. Review flood insurance.
Let’s talk about your home
Help choosing coverage. Support after you buy.
Choose your coverage
We review your home and compare available limits, deductibles, and roof settlement terms. We explain the differences so you can weigh coverage alongside price.
Review and reshop
At renewal or when your needs change, we can review coverage and reshop available options. Tell us about a new roof, an addition, or a change in how you use the home.
Get help with a claim
We help you report a claim, understand the next steps, and follow up with the insurance company when questions arise.
Start with what you know.
You don’t need every answer to get started. Bring these details if you have them:
- Address, approximate size, year built, and how you use the home.
- Roof age and material, plus recent updates.
- Your current policy and renewal date.
- A closing date, lender request, or coverage deadline.
Use our home insurance quote checklist to gather the details.
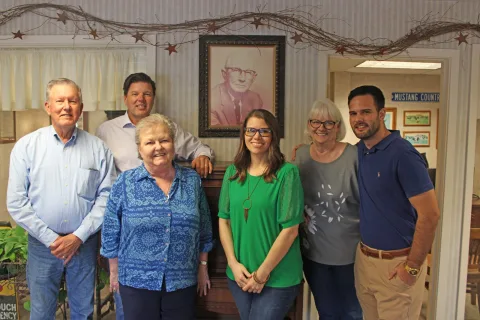
Know what you’re buying before you need it.
Steven and Tyler Stover are licensed property adjusters who have handled catastrophe claims across the country as independent adjusters. That firsthand experience helps us explain roof coverage, deductibles, and exclusions before you choose a policy.
How much does home insurance cost?
Your price depends on the home’s location, rebuilding cost, age and condition, plus your coverage and deductible choices. Claims history can also affect the premium. Compare quotes with the same limits and deductibles to see the price differences clearly.
How can I lower my home insurance premium?
Ask about discounts for an impact-resistant roof, protective devices, or combining home and auto insurance. Compare the total cost and coverage, and choose a deductible you could afford after a loss. Available discounts vary by insurer.
Is homeowners insurance required in Texas?
Texas does not require homeowners insurance by law, but a mortgage lender usually requires it. Check your lender’s coverage requirements before closing or changing an existing policy.
Let’s make sense of your home coverage.
Start online, or call the office and talk it through.
Submitting a quote request does not bind, change, reinstate, or cancel coverage without written confirmation.